CashBook - Balance & Expense
3.8

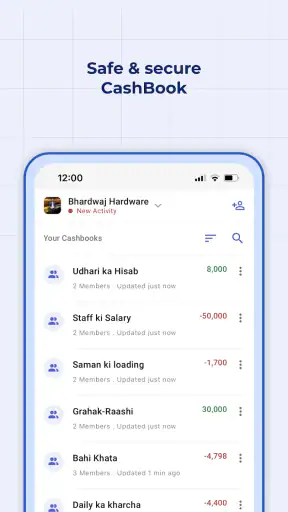
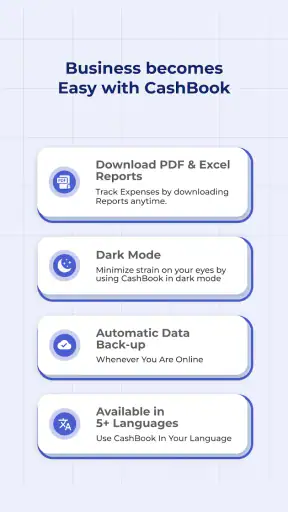
I started using CashBook - Balance & Expense because I wanted a simpler way to follow everyday money movement without turning a small business ledger into a full accounting project. It is a free business app from Obopay – Payment Wallet for Businesses, built around recording income, expenses, and the cash balance that remains after those entries. That focus makes it easier to understand than many finance tools, although it also means the app is best judged as a practical cash book rather than a complete replacement for professional accounting software.
My first impression is that the app is aimed at people who need a clear running record: a shop owner checking the day’s takings, a freelancer separating incoming payments from costs, or a household trying to see where cash is going. The store summary describes cash-flow and daily-balance management, and that is the right way to approach it. I would not install it expecting banking automation, tax preparation, or advanced business reporting. I would install it when the main problem is forgetting small transactions or losing track of the difference between money received and money spent.
It has a 3.8 average from around 207 thousand ratings and more than five million installs, so it is not an obscure experiment with no established audience. The age rating is Everyone, and the app is free to download. There are in-app purchases ranging from $2.49 to $549.99 per item, so I would check the purchase screen carefully before committing to anything beyond the basic experience. The current version is 8.7.3, and it supports Android 7.0 or later.
How CashBook feels during ordinary use
I judge a cash-book app less by how many financial tools it promises and more by whether it helps me build a record I can trust at the end of a busy day. In the next section, I’ll look at the practical habits that make this focused approach useful, including how I’d handle entries when work gets hectic and what that manual workflow asks of the person using it.
A focused starting point instead of a crowded dashboard
The strongest part of the concept is its narrow purpose. When I open a cash-book app, I do not want to navigate through invoicing, payroll, inventory, investment charts, and banking products before I can record a payment. CashBook - Balance & Expense keeps the central question in view: what came in, what went out, and what should the balance look like now?
That makes it approachable for someone who is not comfortable with accounting terminology. A small trader can think in everyday terms such as a sale, a supplier payment, transport, rent, or a personal withdrawal. A freelancer can use the same approach for client income and work-related expenses. The value is not that it replaces financial knowledge; it is that it encourages consistent recording before small transactions disappear from memory.
I found the best results came from treating every entry as a short habit rather than a weekly administrative task. Recording a cost immediately after buying stock or paying for delivery gives a more trustworthy picture than trying to reconstruct the week from receipts and messages. That is a useful, non-obvious advantage of a dedicated cash book: it lowers the mental barrier to logging something small.
A realistic day for a small business owner
Imagine a food stall owner beginning the morning with cash carried over from the previous day. During the day, customers pay for items, a supplier receives payment, and the owner buys packaging from a nearby store. Instead of keeping these amounts in a notebook and hoping the total is correct later, the owner can record each movement as it happens and use the balance as a running checkpoint.
The important workflow is not simply entering sales. It is recording the less memorable expenses too. A few small purchases can make the final cash position look wrong if they are skipped. I would use a short note for each entry, keep business and personal spending separate, and review the day before closing rather than waiting until the end of the week. This is where the app feels more useful than a loose spreadsheet: it is designed around the repeated act of maintaining a cash record.
For a freelancer, the same method works differently. I would record a client payment when it actually arrives, not when an invoice is sent, and enter software, travel, or equipment costs separately. That distinction helps prevent an optimistic balance based on money that is expected but not yet received. The app can support that discipline, but it cannot make the accounting decision for you; the quality of the result still depends on how consistently and accurately entries are made.
Speed expectations and the feel of repeated entries
For this type of tool, perceived speed matters less than it does in a game, but it still affects whether I keep using it. A cash book needs to feel quick enough that opening it is easier than postponing the entry. In my experience, the most important test is not the first launch. It is the repeated sequence of entering several transactions during a busy day, checking the balance, and returning later without losing the thread.
CashBook is most convincing when used for short, focused sessions. I would not expect it to perform heavy calculations or render a complex visual dashboard, because its purpose is straightforward record keeping. That simplicity should help it feel less demanding than a broad accounting suite, particularly on an older Android phone that still meets the minimum system requirement.
There is a practical trade-off here. A smaller, focused interface can make common actions easier, but it may also require more manual judgment. If you need automatic bank imports or a sophisticated reconciliation process, a dedicated accounting service will probably save more time despite having a heavier interface. CashBook makes sense when manual entry is acceptable and the main goal is a dependable daily overview.
What happens during heavy-use moments
The app’s most demanding realistic situation is not a single complicated calculation. It is a busy period in which many transactions need to be entered close together, perhaps while serving customers or moving between jobs. In that situation, the biggest performance risk is user friction: a form that takes too long to complete, a balance that is hard to interpret, or a workflow that encourages postponing entries.
My advice is to create a consistent entry routine before the busy period begins. Decide which wording you will use for recurring expenses, record transactions in the same order each time, and review the balance after the rush. This reduces mistakes and makes later checking easier. It also exposes a limitation of any manual cash book: if several people handle the same cash and only one person records it, the app cannot automatically know which transaction was missed.
For a growing business with many daily sales, this is where I would be cautious. A simple cash book can remain useful as a high-level cash log, but it may become tedious if every sale must be entered individually. A point-of-sale system or bookkeeping platform may be a better fit when transaction volume, staff access, stock control, or formal reports become central requirements.
Reliability depends on the habit around the app
I see reliability in two parts. First, the application needs to open and accept entries consistently. Second, the record needs to remain meaningful when I return to it later. Even a stable app produces a misleading balance if I enter expenses days late, mix personal and business cash, or use vague descriptions that I cannot recognize at the end of the month.
That is why I would use a short end-of-day check as part of the workflow. Compare the app’s balance with the cash or account amount you are actually tracking, then investigate differences while the details are still fresh. This is more useful than waiting for a large discrepancy to accumulate. The app gives you a place to maintain the record; it does not remove the need for basic cash control.
Recovery is another reason to be deliberate. Before relying on any financial record, I would learn how the app handles backups, exports, account changes, and device replacement from within its current interface. I would also avoid treating it as the only copy of important business information. Keeping receipts or another appropriate record is sensible, especially when the entries may later matter for tax, reimbursement, or a dispute.
That recommendation is not a criticism unique to CashBook. Manual finance apps are vulnerable to incorrect input, forgotten entries, and device-related problems. The difference is that a focused app can encourage frequent updates, while a complex system may provide stronger formal controls at the cost of setup time. Choose according to the consequence of an error, not just the convenience of the interface.
Device constraints and who should be careful
Support for Android 7.0 or later makes the app accessible to people who do not own a recent phone. That is valuable for a basic business utility, particularly when the device is used mainly for calls, messaging, and daily records. I would still keep reasonable free storage available and update the operating system when the phone supports it, because general device health affects every app’s responsiveness.
Older hardware can be perfectly adequate for a cash book, but the surrounding conditions matter. A phone with very limited memory, an overloaded storage drive, or aggressive battery management may interrupt any app’s workflow. If entries are being made in a shop or outdoors, I would also test the app in the exact environment where it will be used rather than assuming that a comfortable home setup represents the daily experience.
The Everyone rating makes the app suitable for a broad audience from an age-classification perspective, but that should not be confused with suitability for every financial situation. A child learning to track pocket money has different needs from a business owner who must maintain records for compliance. The app may be easy to approach, yet the responsibility for using accurate categories and retaining supporting documents remains with the user.
Three practical techniques that improve the result
My first technique is to separate “cash available” from “money expected.” If a customer has promised to pay later, I would not count that amount as received. Recording income only when it is actually available produces a more honest daily balance and prevents spending decisions based on future money.
Second, I would use descriptions that answer the question I will ask later: “What was this for?” A note such as “expense” is nearly useless after several weeks. “Packaging,” “fuel for delivery,” or “market purchase” gives the entry a purpose. This small change makes review faster and helps reveal recurring costs that are easy to overlook.
Third, I would establish a closing routine for days when several people handle money. One person should compare the physical cash with the recorded balance, while another person can check receipts or payment messages if the business is large enough to justify that separation. CashBook can organize the record, but a clear responsibility for closing it is what makes the record dependable.
Where it beats a notebook or spreadsheet
A paper notebook is flexible, familiar, and works without a battery. It can also become difficult to total, search, or correct neatly. A spreadsheet offers more control and can support custom formulas, but it asks the user to design the structure and maintain it. For someone who wants a ready-made place to follow income, expenses, and balance, CashBook sits between those options.
Its advantage over a notebook is the possibility of a more organized running view. Its advantage over a spreadsheet is reduced setup. The trade-off is flexibility: a spreadsheet can be shaped around departments, projects, tax categories, or complex reporting, while this app is more appealing when the cash record itself is the priority.
Compared with full accounting software, the difference is even clearer. Accounting platforms are better for invoices, formal ledgers, multiple users, reconciliation, inventory, and reports required by an accountant. They can also demand more configuration and training. I would choose CashBook for a solo operator or very small activity where the immediate need is visibility, not a complete financial system.
Who should use it and who should skip it
I would recommend it to a person who repeatedly asks, “Where did the cash go today?” and wants a simple routine for answering that question. It is especially suitable for small shops, independent workers, side businesses, and anyone who prefers manual control over automatic financial connections. The free entry point also makes it easy to test whether a digital cash book fits your habits before moving to a larger tool.
I would skip it if your records must support formal accounting workflows, detailed tax preparation, inventory management, payroll, or several staff members entering transactions at the same time. I would also look elsewhere if you refuse manual entry. In that case, the convenience of automated imports may matter more than the simplicity of a focused ledger.
Potential purchasers should remember that the app is free to download but includes in-app purchase items, with prices that can extend from a few dollars to several hundred dollars. I would identify exactly what a paid item provides and whether it is necessary for your workflow before confirming a purchase. For basic cash tracking, the sensible approach is to begin with the core experience and judge it by the quality of the record it helps you maintain.
My performance verdict
CashBook - Balance & Expense succeeds when I treat it as a lightweight daily cash-control tool rather than an all-purpose finance platform. Its focused purpose should make ordinary use approachable, and its compatibility with Android 7.0 or later gives it a practical reach across older devices. The main performance question is not whether it can replace a large accounting system; it is whether it lets you record and review transactions without making the habit feel burdensome.
My honest verdict is positive for the right audience. I would choose it for a small, manually managed cash flow where quick daily visibility matters more than advanced automation. I would keep a separate backup or supporting record for important information, establish a closing routine, and check the purchase details before paying for extras. The app is most valuable when it turns scattered small transactions into a consistent habit, and that is a narrower promise than full bookkeeping—but a useful one when it matches your needs.
3.8
475.00 Reviews
Pros
- Simple interface makes daily income and expense tracking quick.
- Supports multiple accounts for separating cash
- bank
- and wallet balances.
- Custom categories help organize spending according to personal needs.
- Useful summaries make it easier to identify spending patterns over time.
- Backup and restore options help protect financial records when changing devices.
Cons
- Some advanced tools may require a paid upgrade or premium subscription.
- Manual entry can become time-consuming for users with many daily transactions.
- Limited automation may require frequent updates to recurring expenses.
- Financial data accuracy depends entirely on consistent user input.
- Users may need to review privacy settings before storing sensitive money records.


